Kohat Cement Company Limited (PSX: KOHC) was established by State Cement Corporation of Pakistan in 1984. In 1992, the government privatized the company. The company was listed on the stock exchanges of Pakistan in 1984.
The principal activity of the company is the manufacturing and sale of cement [grey and white clinker]. ANS Capital [Private] Limited is the holding company of KOHC.
Pattern of Shareholding
As of June 30, 2026, the company has 919.306 million shares outstanding which are held by 8121 shareholders. Associated companies, undertakings and related parties have the majority stake of 60.17 percent in company followed by Directors, CEO, their spouse and minor children holding 18.34 percent shares of the company.
Local general public has a stake of 9.19 percent in the company followed by Mutual Funds holding 9.01 percent shares. Joint stock companies have 1.15 percent stake in KOHC. The remaining shares are held by other categories of shareholders.
Historical Performance (2021-26)
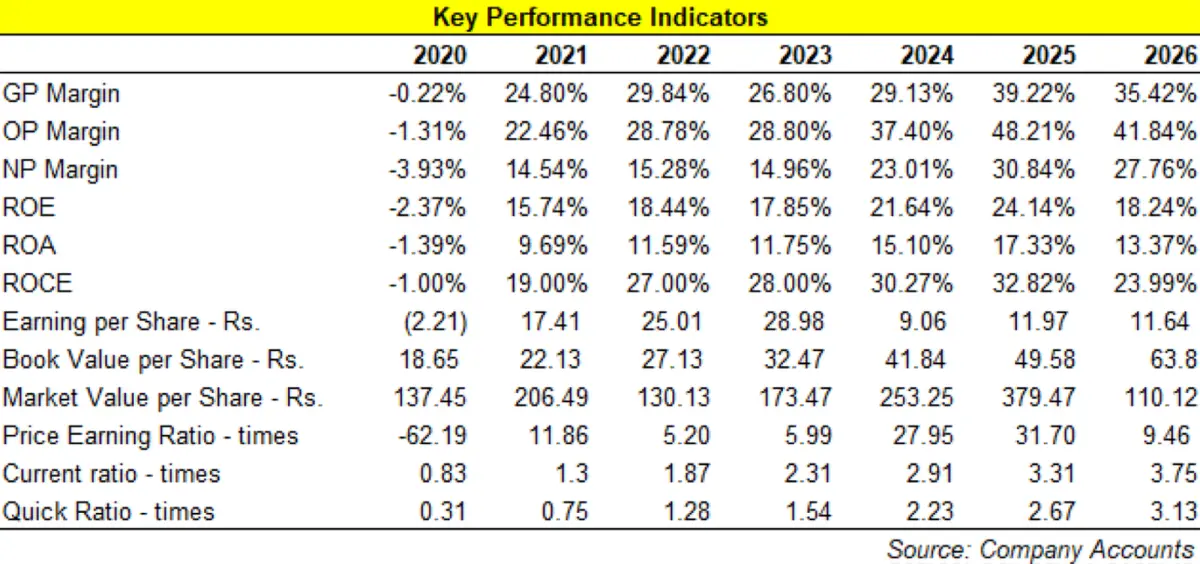
Over the period under consideration, KOHC’s topline posted year-on-year dip in 2024 and 2025. In 2020, KOHC posted gross, operating and net losses. The company’s bottomline exhibited growth thereafter until 2025 followed by a decline in 2026. KOHC’s margins which followed a downward trajectory until 2020 posted a rebound for the next two years.
In 2023, KOHC’s margins slightly ticked down, however, bounced back to attain their highest levels in 2025. In 2026, KOHC’s margins notably fell. The detailed performance review of the period under consideration is given below.
In 2021, KOHC’s topline boasted 112.89 percent year-on-year growth to clock in at Rs.24,057.38 million. This was backed by 69.30 percent year-on-year growth in cement off-take.
The growth was propelled by government initiatives for the real-estate sector including low-cost housing projects and subsidized house financing along with CPEC related activities during the year. Improved selling prices during the year proved to be a cherry on top resulting in gross profit of Rs.5965.35 million in 2021 with GP margin of 24.80 percent. This was against the gross loss of Rs.24.32 million recorded in 2020.
KOHC took optimum benefit of the increased market demand and made its new production line fully operational in 2021.
Distribution expense mounted by 46.54 percent in 2021 due to higher payroll expense and extensive sales promotion drives undertaken during the year. To activate its new production line, the company hired additional resources which took the tally from 683 employees in 2020 to 696 employees in 2021.
Other expense grew by 1876.81 percent in 2021 mainly owing to higher provisioning done for WPPF and WWF. Other income slid by 13 percent in 2021 due to lower foreign currency gain and lesser realized gain on investment at FVTPL. KOHC posted operating profit of Rs.5403.01 million in 2021 with OP margin of 22.46 percent. This was against the operating loss of Rs.147.61 million registered in 2020.
High interest rates paved the way for finance cost to grow by 26.20 percent year-on-year in 2021. This was despite the fact that the company paid off a huge portion of its outstanding liabilities during the year which resulted in its gearing ratio falling down from 32.82 percent in 2020 to 8.89 percent in 2021.
KOHC registered net profit of Rs.3497.51 million in 2021 with EPS of Rs.17.41. NP margin clocked in at 14.54 percent in 2021. This was against the net loss of Rs.443.74 million and loss per share of Rs.2.21 recorded in 2020.
In 2022, KOHC’s topline picked up by 36.66 percent to clock in at Rs. 32,876.95 million. However, the growth was price-led rather than volume-led. Local and domestic sales posted decline of 0.5 percent and 95.6 percent respectively in 2022. Prices had to be kept high to absorb the exorbitant rise in prices of coal, electricity and petroleum products.
The company used a mix of local and Afghan coal to mitigate the effect of elevated international coal prices. Such measures enabled KOHC to improve its GP margin to 29.84 percent in 2022. In absolute terms, gross profit strengthened by 64.48 percent in 2022.
Distribution expense surged by 29.70 percent in 2022 due to higher salaries and wages paid during the year. Although number of employees remained intact during the year, inflationary pressure resulted in 12.76 percent spike in administrative expense in 2022.
Other income improved by 304.36 percent in 2022 mainly on account on realized gain on investment in treasury bills. Other expense escalated by 73.10 percent in 2022 due to higher profit related provisioning.
KOHC’s operating profit grew by 75.15 percent in 2022 with OP margin clocking in at 28.78 percent. Finance cost grew by mere 4 percent year-on-year in 2022 despite multiple upward revisions in discount rate taken place during the year. This was because the company paid its entire short-term loans during the year. Moreover, massive increase in short-term investment resulted in negative gearing ratio in 2022.
Bottomline of KOHC registered 43.65 percent year-on-year growth in 2022 to clock in at Rs. 5024.28 million in 2022 with EPS of Rs.25.01 and NP margin of 15.28 percent.
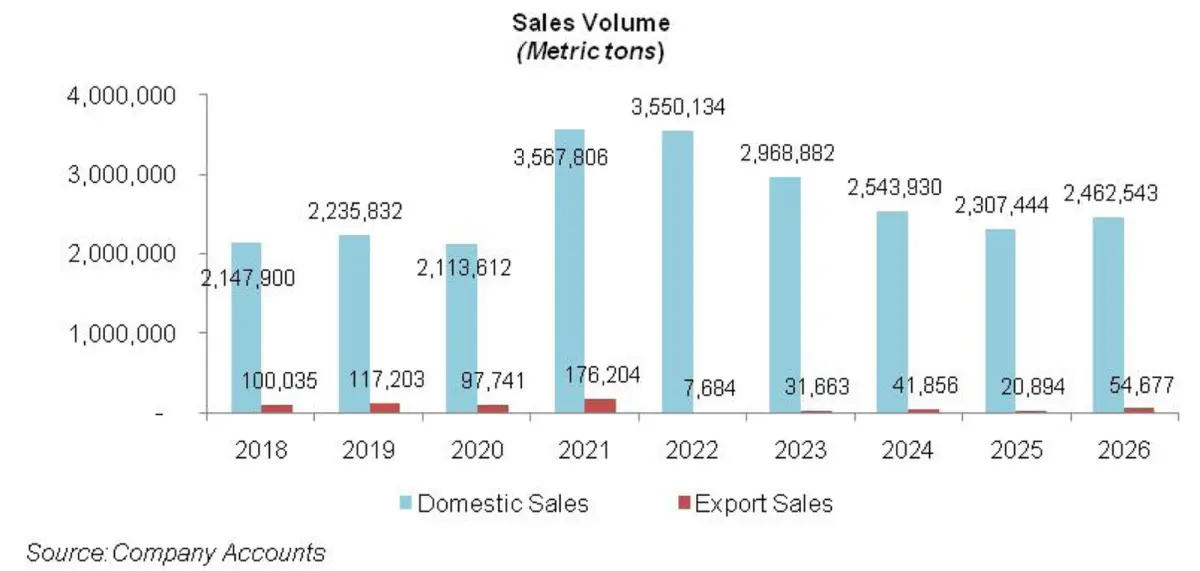
Mounting economic and political instability resulted in a standstill in construction and infrastructure related activities in the country. This translated into 15.71 percent decline in the overall dispatches of cement industry. KOHC’s sales volume ticked down by 15.66 percent in 2023 to clock in at 3 million M tons. On the positive front, export sales grew by over 312 percent in 2023 to clock in at 31663 M tons.
However, it constituted only 1 percent of the total sales volume of KOHC in 2023. KOHC’s topline picked up by 18.39 percent to clock in at Rs. 38,921.64 million in 2023. Spike in the prices of petroleum, coal, electricity and imported consumables was further exacerbated due to Pak Rupee depreciation.
The company tried to control its cost by setting up a solar power plant and switching to cheaper local and Afghan coal.
However, its GP margin ticked down to 26.8 percent in 2023 with only 6.33 percent increase in gross profit in absolute terms. Distribution expense mounted by 44.20 percent in 2023 due to heightened salaries and sales promotion expense incurred during the year. Number of employees remained intact at 696 in 2023, however, inflationary pressure pushed up administrative expense by 12.10 percent in 2023.
Other income picked up by 202.23 percent in 2023 mainly on account of hefty dividend received from investment in mutual funds. Higher profit related provisioning drove up other expense by 30.81 percent in 2023. KOHC recorded 18.46 percent taller operating profit in 2023 while maintaining its OP margin at 28.80 percent.
Finance cost surged by 37.68 percent in 2023 due to monetary tightening. Net profit improved by 15.85 percent in 2023 to clock in at Rs.5820.75 million with EPS of Rs.28.98 and NP margin of 14.96 percent.
In 2024, KOHC’s net sales dipped by 0.7 percent to clock in at Rs.38,647.77 million in 2024. This was on the back of 13.82 percent lesser dispatches recorded by the company during the year on account of economic slowdown. Export sales ticked up by 32.19 percent to clock in at 41856 metric tons, standing at 1 percent of KOHC’s total sales volume.
Increase in cement prices, change in coal mix coupled with the stability in the value of local currency resulted in 7.9 percent uptick in gross profit in 2024 with GP margin climbing up to 29.13 percent.
Distribution expense ticked up by 12 percent in 2024 due to inflationary pressure. Higher payroll expense resulted in 23.17 percent spike in administrative expense in 2024. Other income strengthened by 113.46 percent in 2024 mainly on account of dividend received from investment in mutual funds. Lesser profit related provisioning translated into 22.34 percent decline in other expense in 2024.
The company registered 28.94 percent higher operating profit in 2024 with OP margin climbing an unprecedented level of 37.4 percent – thanks to substantial other income. KOHC was able to cut down its finance cost by 8.50 percent in 2024 by squeezing its loan portfolio on the back of strong liquidity position. As of June 30 2024, the company had no short-term loans outstanding and its long-term loans also ticked down.
KOHC posted net profit of Rs.8893.46 million in 2024, up 52.79 percent year-on-year. This translated into EPS of Rs.9.06 and NP margin of 23 percent. It is to be noted that the company’s EPS fell despite higher net profit in 2024. This was because each ordinary share of the company having a face value of Rs.10 each was split into five ordinary shares of Rs.2 each.
In 2025, KOHC recorded year-on-year decline of 2.88 percent in its topline which clocked in at Rs.37,535.70 million. This came on the back of 9.96 percent dip in the overall dispatches of the company in 2025. Not only did local sales slid by 9.30 percent in 2025 due to lesser demand from residential and commercial projects, export sales also deteriorated by 50 percent due to high regional competition (see the graph of sales volume). Cement prices continued to hike to account of elevated cost.
This coupled with cost control initiatives such as commissioning of 5.34 MW solar power project, commencement of the construction of coal fired power project and efficient sourcing of coal and fuel resulted in 16.71 percent dip in cost of sales in 2025.
KOHC recorded 30.78 percent improvement in its gross profit in 2025 with GP margin attaining its optimum level of 39.22 percent. Distribution expense mounted by 14.37 percent in 2025 due to higher salaries of sales force.
Administrative expense also surged by 42.52 percent in 2025 due to higher payroll expense as well as legal & professional charges incurred during the year. KOHC expanded its workforce from 715 employees in 2024 to 723 employees in 2025.
Higher provisioning done for WWF and WPPF resulted in 64.41 percent spike in other expense in 2025. Other income registered 18.60 percent improvement in 2025 on the back of realized gain on investments at FVTPL.
Operating profit improved by 25.21 percent in 2025 with OP margin jumping up to 48.21 percent. Finance cost descended by 48.34 percent in2025 due to monetary easing. Net profit multiplied by 30.15 percent to clock in at Rs.11,575.15 million in 2025. This translated into EPS of Rs.11.97 and NP margin of 30.84 percent in 2025.
In 2026, KOHC’s topline ticked up by 2.65 percent to clock in at Rs.38,530.65 million. This came on the back of 8.11 percent enhancement in the company’s sales volume which clocked in at 2.517 million tons in 2026.
While local sales inched up by 6.72 percent during the year, export sales registered a splendid growth of 161.69 percent. However, export sales constituted a thin 2.17 percent of the company’s overall sales volume in 2026. Cost of sales surged by a much greater magnitude of 9 percent in 2026 due to higher coal and energy prices.
This coupled with intense competition and lower cement prices suppressed KOHC’s gross profit by 7.29 percent in 2026 with GP margin falling down to 35.42 percent. Distribution expense surged by 11 percent in 2026 due to greater sales volume. Administrative expense also escalated by 54 percent during the year due to higher payroll expense, travelling & conveyance charges as well as repair & maintenance charges incurred during the year. KOHC expanded its workforce to 748 employees in 2026.
Lower gain realized on investments in mutual funds, decline in the fair value of financial assets and thinner scrap sales squeezed other income by 12 percent in 2026. Other expense also slid by 7.67 percent in 2026 due to lesser provisioning done for WWF and WPPF. KOHC registered 10.92 percent plunge in its operating profit in 2026 with OP margin falling down to 41.84 percent. It is to be noted that the company’s robust other income has been ensuring an operating profit greater than gross profit since 2023.
Finance cost dwindled by 56.15 percent in 2026 due to lower average borrowing rate. This was despite greater outstanding debt at the end of the year. Net profit plummeted by 7.59 percent to clock in at Rs.10,696.85 million in 2026. This translated into EPS of Rs.11.64 and NP margin of 27.76 percent in 2026.
Recent Performance (1QFY27)
During the first quarter of the ongoing fiscal year, KOHC’s topline posted a reasonable 15 percent year-on-year growth to clock in at Rs.11,837.40 million. Domestic dispatches grew by 4.4 percent during the period under review; however, it was offset by thinner export sales, resulting in 3 percent decline in the overall dispatches.
Topline growth was the result of stronger retention prices and improved sales mix. These factors offset the impact of higher international coal prices and culminated into 39.78 percent stronger gross profit in 1QFY27. GP margin clocked in at 41.78 percent in 1QFY27 versus 34.39 percent in 1QFY26.
Distribution expense inched up by only 1.63 percent in 1QFY27 due to closure of Afghan border which greatly impacted export sales. Inflationary pressure and the expansion of the company’s operations resulted in 12.61 percent hike in administrative expense in 1QFY27.
Lower dividend income appears to be the cause of 36 percent plunge in other income recorded during the period. Conversely, other expense mounted by 44.22 percent in 1QFY27 likely due to greater provisioning done for WWF and WPPF. Operating profit strengthened by 15.92 percent in 1QFY27 with OP margin clocking in at 44.32 percent versus 44 percent recorded in 1QFY26.
Despite the onset of monetary tightening, finance cost dropped by 30.46 percent in 1QFY27 due to lower outstanding liabilities at the end of the period. Net profit clocked in at Rs.3313.04 million in 1QFY27, up 12.54 percent year-on-year. This translated into EPS of Rs.3.60 and NP margin of 28 percent in 1QFY27. This was against the EPS of Rs.3.20 and NP margin of 28.62 percent recorded in 1QFY26.
Future Prospects
Projected rise in local demand alongside higher pricing power will enable the cement companies to keep their toplines and margins buoyant in 2027. Cost control measures such as the recently commissioned 2.32 MW solar power project and the upcoming 28.5 MW coal fired power project will keep the cost in check and provide energy self sufficiency. KOHC will also keep benefiting from its sizeable other income.
Source: brecorder
Leave a Reply